
Florida construction-to-permanent loans
Build your Florida home. Close once.
“If another lender said no, call me. That’s most of my business.”
One loan covers your Florida build and your long-term mortgage. One application, one approval, one closing.
A preferred lender with builders around South Florida.
Building outside Florida? Neil is licensed in 18 states. Ask about your build.
Who it's for
Six ways people use it
You own the land
The equity in your lot can help finance the build.
You found a lot and a builder
Buy the lot and finance the build from day one, once your plans and specs are ready.
You're building a second home
The beach, lake or mountain house.
You're building a rental
Investment properties are eligible too.
You're tearing down to rebuild
An older house on a great lot.
Your assets do the talking
Retirees and business owners can use assets to qualify.
Estimate your loan
Do your numbers work?
Slide or type your numbers for a quick estimate of the loan you'd need and how it compares to our loan-to-value limits.
Any mortgage or lot loan balance. Enter 0 if it is paid off.
Your builder's contract price.
+ 10% contingency:
What the finished home should appraise for.
- Loan needed
- Estimated max loan
Estimate only, for illustration. This is not a loan approval, a commitment to lend or a rate quote. Your actual loan amount depends on the appraisal, credit approval, underwriting and program guidelines, which can change. Loan-to-value limits shown are for a primary residence you will live in. Second homes and investment properties have different limits; call Neil for those.
How it works
Close once. Build. Move in.
Close once
One application, one approval and one closing covers the build and your mortgage.
Build with draws
Your builder is paid in stages as work is finished and verified.
Settle into your mortgage
When the house is done, the loan becomes your long-term mortgage. No second closing.
Building in Florida
What a Florida build adds to the plan
Building in Florida brings a few questions buyers in other states don't always face. Your builder, your insurance agent and the local building department have the final word on each one. Here's what to ask about early.
Hurricane building code
Florida has its own building code, including wind standards for hurricanes. Your builder designs to the code that applies where you're building. Ask how your plans meet the local wind requirements.
Flood zones and elevation
Your lot's flood zone can affect how the home is built, including how high the first floor sits, and whether flood insurance is required. Check the flood zone before your plans are final.
Insurance during construction
You'll need the right coverage in place while the house is being built, such as builder's risk, and in some areas flood or wind coverage. Talk with an insurance agent before closing so it's lined up early.
Permits and timelines
Permit review times vary by county and city, and they can change during the year. Your builder's schedule should allow for local permitting, since that schedule also sets your interest-only period.
We look at your lot, your builder and your plans together, so these questions come up early.
Program highlights
What the loan covers
Built for people who want one lender from the first draw to the long-term mortgage.
- Primary homes, second homes and investment properties
- Land equity can count toward your build
- Interest-only payments while you build
- Adjustable-rate options when construction ends: 3/1, 5/1 and 10/1
- Draws paid directly to your builder, managed by Neil's team
The draw process
Your builder gets paid as the work gets done.
You don't hand your builder a check and hope.
Your builder gets a draw schedule before work starts. As each stage is finished, the work is verified and the draw goes straight to the builder. Neil's team runs every draw in-house, so you and your builder deal with one team from closing to the last draw.
Example draw schedule
- FoundationSite work, footings and slab.
- FramingWalls, floors and roof structure.
- Dry-inRoof, windows and doors in place.
- InteriorPlumbing, electrical, drywall and finishes.
- FinalCertificate of occupancy and the last draw.
Each draw is paid to your builder after that stage is verified. Your builder sets the actual stages and amounts.
What you'll need
Start gathering early
Your usual income, asset and ID documents, plus your builder's contract, plans and insurance.
- Fully executed construction contract
- Your builder's draw schedule
- Specs and plans
- Contractor's license and insurance
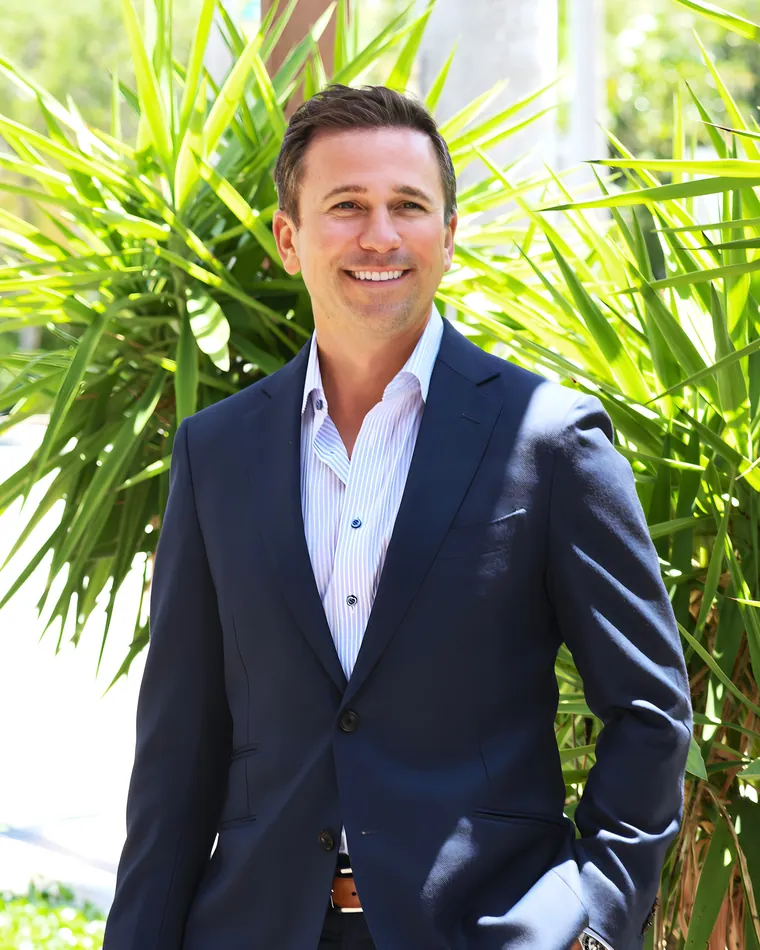
About Neil
Someone who has done it before.
Neil Bourdelaise has spent 23 years in mortgage lending and leads The Bourdelaise Team from Delray Beach, Florida. Builders around South Florida work with him as a preferred lender. His job is to make a complicated loan feel simple: you'll know what's next at every stage of your Florida build.
Complex loans, simple experience.
Questions
What people ask first
What is a construction-to-permanent loan?
One loan that pays for building your home and then becomes your long-term mortgage. You apply once, get approved once and close once.
What do I pay while the house is being built?
Interest-only payments for 12 or 18 months, depending on your builder's construction schedule.
How do draws work?
Your builder sets a draw schedule before work starts. As each stage is finished, the work is verified and that draw is paid directly to the builder.
Can I use land I already own?
Yes. The equity in your lot can help finance the build. How much counts depends on the lot's value, what you owe on it, and your file.
Can I build a second home or a rental?
Yes. Primary homes, second homes and investment properties are all eligible.
Talk to Neil
Ready to talk about your build?
Tell us where you're building and when. We'll tell you what it takes, plainly.
About 2 minutes
Tell us about your build
A few quick questions about your land, your builder and your timing. Then pick a time to talk with Neil.
See if your build fitsPlease don't send Social Security numbers or account details here.